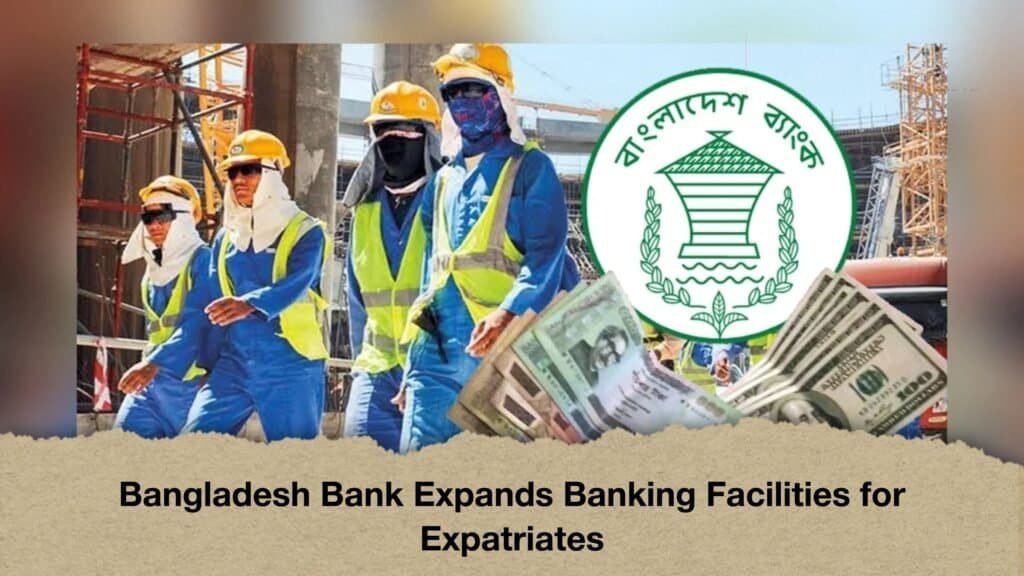
Bangladeshi expatriates will have greater flexibility in managing their money at home under revised rules for Non-Resident Convertible Taka Accounts (NRCTAs), introduced by Bangladesh Bank. The changes allow expatriates to open and operate accounts from abroad, invest in Bangladesh, obtain loans against their deposits and repatriate their principal funds along with the interest or profit earned.
The central bank expects the revised arrangements to make banking services more accessible to Bangladeshis living overseas, encourage the secure management of their hard-earned money and expand opportunities for legitimate investment in the country.
The new provisions were outlined in a notice published on Bangladesh Bank’s official Facebook page on Friday night, 10 October.
More Banks Available for Account Opening
Under the revised rules, expatriates can open NRCTA accounts through authorised dealer (AD) banks in addition to offshore banking units. This expansion gives non-resident Bangladeshis more options when choosing a banking institution to manage their funds.
Account holders can also choose from three types of accounts: savings, current and fixed deposit accounts. The available options allow customers to select an account according to their financial needs, whether they wish to save money, conduct regular transactions or keep funds deposited for a specified period.
The terms and conditions set by individual banks will apply to the opening and operation of these accounts.
Online Account Opening and Management
One of the key changes is the opportunity to open and operate NRCTA accounts through online and electronic banking services while living abroad.
Previously, managing certain banking activities could require expatriates to deal directly with banks in Bangladesh. The expanded digital facilities are expected to reduce the need to travel to the country solely to complete banking transactions.
This could be particularly useful for overseas workers and other expatriates who face difficulties arranging visits because of work commitments, travel costs or other practical constraints.
However, customers will still need to comply with the relevant identification, documentation and verification requirements imposed by their banks and applicable regulations.
Multiple Ways to Deposit Money
The revised arrangements provide several channels for depositing funds into NRCTA accounts. Expatriates can transfer their overseas earnings through banks, exchange houses and money transfer operators. They can also move funds from their own foreign currency accounts into an NRCTA account.
These options are expected to make it easier for non-resident Bangladeshis to transfer and retain their earnings within the country’s formal banking system.
Greater access to regulated banking channels can also support transparency in financial transactions and encourage expatriates to keep their savings in authorised institutions.
Spending and Investment Opportunities in Bangladesh
Money deposited in an NRCTA account can be used for personal expenses in Bangladesh, transferred to other accounts or invested in sectors approved by the government.
The facilities may help expatriates manage household expenses, meet personal financial obligations and allocate funds to eligible investment opportunities without having to return to Bangladesh.
The expanded arrangements could also create more opportunities for expatriates to channel their savings into legitimate economic activities. Any investment, however, must comply with the relevant sector-specific requirements, approvals and applicable regulations.
Loans Against Deposited Funds
Under the revised rules, expatriates will be able to use money held in their NRCTA accounts as collateral to obtain bank loans.
This facility could provide greater financial flexibility for account holders who need funds for specific purposes but prefer not to withdraw their savings immediately.
Loan approval will remain subject to the lending bank’s policies, assessment of the proposed collateral and other applicable conditions. Holding money in an NRCTA account will not automatically guarantee access to credit.
Principal and Earnings Can Be Repatriated
Another significant feature of the revised arrangements is the ability to repatriate the principal deposited in an NRCTA account, along with the interest or profit earned on it, when required.
This provision offers expatriates greater flexibility in managing savings across countries. They can retain funds in Bangladesh for local expenses or investment while having the option to transfer eligible amounts abroad when their financial circumstances change.
The repatriation process will remain subject to applicable foreign exchange regulations and the procedures prescribed by the relevant banking authorities.
A Move to Simplify Expatriate Banking
Bangladesh Bank’s initiative is aimed at making banking more convenient for expatriates, improving access to financial services and encouraging the use of savings for authorised investment in Bangladesh.
Remittances from Bangladeshis working overseas play an important role in the country’s economy. Besides supporting household expenditure, these funds can contribute to savings, business activities and other forms of investment.
By expanding access to account-opening facilities, digital banking, credit against deposits and fund repatriation, the revised rules could make it easier for expatriates to manage their finances without being physically present in Bangladesh.
The effectiveness of the changes will depend partly on how efficiently banks implement the new arrangements, including digital account services, customer verification and fund transfers.
Expatriates are advised to check the relevant circular issued by Bangladesh Bank and consult their chosen bank to understand the documentation requirements, account conditions and procedures applicable to their individual circumstances.