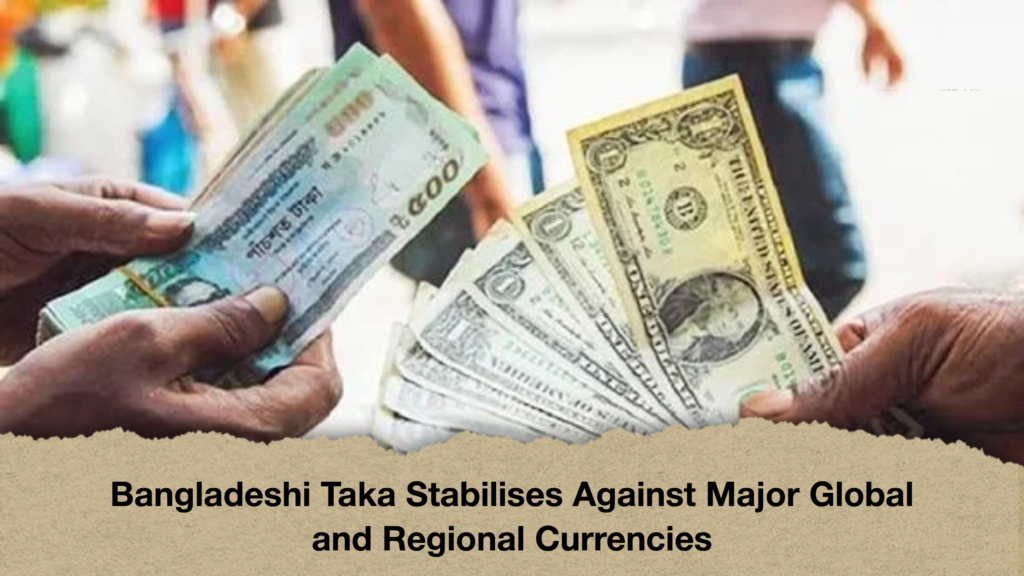
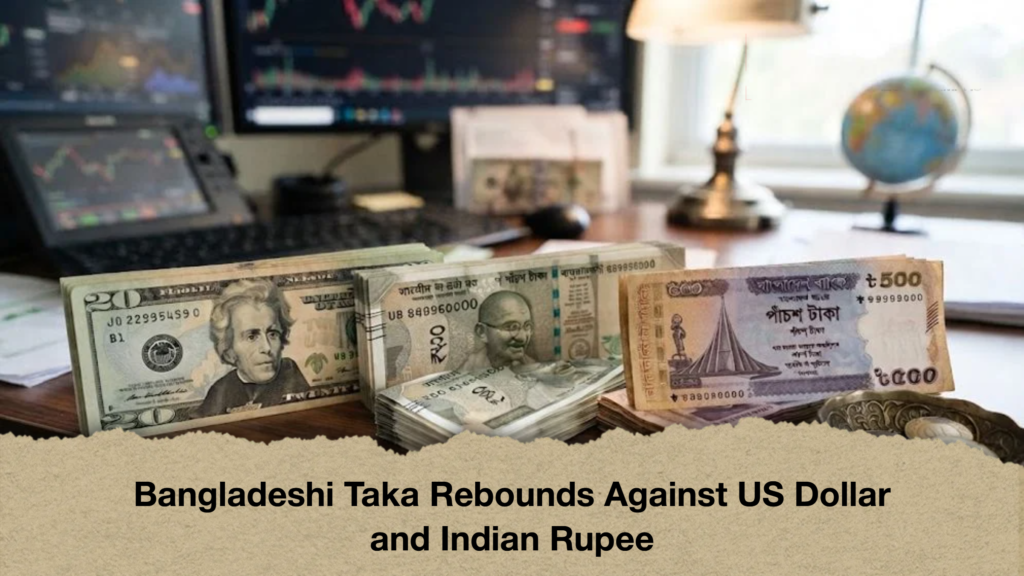
Following a relentless five-and-a-half-year decline, the Bangladeshi taka is demonstrating unexpected firmness against the US dollar, signaling a potential turning point in the nation’s foreign exchange dynamics.
Latest exchange metrics published by Bangladesh Bank confirm that the domestic currency reached its most robust valuation relative to the dollar in several years during the second half of 2026. Point-to-point data reveals that the taka appreciated by 0.06 per cent against the greenback between June 2025 and June 2026. Momentum picked up significantly towards late summer, with the currency gaining an additional 0.77 per cent in just three weeks between late August and mid-September. The official exchange rate eased from Tk 123.95 per dollar down to Tk 123.00.
This recovery follows a prolonged spell of currency depreciation. In 2021, the US dollar traded at Tk 85.80 before climbing continuously over subsequent years to peak at Tk 123.95—a staggering drop in taka value of Tk 38.20, or 45.05 per cent. The tide began to turn late in August 2026. Recent spot reference data from the central bank listed the reference rate at Tk 122.9951, while the weighted average rate across the interbank market closed at Tk 122.74.
A substantial recovery in foreign currency reserves and steady remittance inflows have underpinned this domestic rebound. Gross international reserves, evaluated under the International Monetary Fund’s BPM6 methodology, expanded to $31.36 billion in early September 2026, up sharply from $25.68 billion recorded during the same period a year earlier.
Despite these positive markers, liquidity conditions remain tightly managed. Broad import demand required Bangladesh Bank to intervene directly on 14 September, selling $11.50 million to six commercial banks—its first intervention of this nature after a 14-month hiatus. Balancing supply and demand within local interbank channels remains critical to sustaining this recent stability.
| Economic & Exchange Rate Metric | Historical / Baseline | Period / Date | Recent Level / Value | Comparison / Period |
| USD/BDT Exchange Rate (Peak) | Tk 85.80 | 2021 | Tk 123.95 | Late August 2026 |
| USD/BDT Spot Reference Rate | Tk 123.95 | Late August 2026 | Tk 122.9951 | 21 September 2026 |
| USD/BDT Interbank Weighted Rate | Tk 123.95 | Late August 2026 | Tk 122.74 | 21 September 2026 |
| BDT Appreciation vs USD (1-Year) | Baseline | June 2025 – June 2026 | +0.06% | Point-to-Point |
| BDT Appreciation vs USD (3-Week) | Tk 123.95 | 30 August 2026 | +0.77% (Tk 123.00) | 17 September 2026 |
| Foreign Exchange Reserves (BPM6) | $25.68 Billion | September 2025 | $31.36 Billion | September 2026 |
| Central Bank Dollar Sale | $0.00 | 14-Month Pause | $11.50 Million | 14 September 2026 |
| INR/BDT Cross Exchange Rate | ~Tk 140.00 per 100 INR | Historical Peak | Tk 128.00–130.00 | September 2026 |
| INR Spot Rate in BDT | Tk 1.40 | Previous Peak | Tk 1.28 | 21 September 2026 |
| Indian Rupee Movement vs USD | Baseline | June 2025 – June 2026 | -9.50% | Central Bank Data |
| Sri Lankan Rupee Movement vs USD | Baseline | June 2025 – June 2026 | -10.00%+ | Central Bank Data |
| Indonesian Rupiah Movement vs USD | Baseline | June 2025 – June 2026 | -9.00% | Central Bank Data |
| Malaysian Ringgit Movement vs USD | Baseline | June 2025 – June 2026 | +4.00% | Central Bank Data |
| Chinese Yuan Movement vs USD | Baseline | June 2025 – June 2026 | +4.00% | Central Bank Data |
Regional trade dynamics reflect similar shifts. The taka strengthened noticeably against the Indian rupee, moving from a historic high near Tk 140 per 100 Indian rupees down to a range of Tk 128 to Tk 130. As of 21 September, 1 Indian rupee traded at approximately Tk 1.28.
Analysts stress that regional currency weakness plays a central role in this cross-rate realignment. Between June 2025 and June 2026, the Indian rupee fell 9.5 per cent against the US dollar. During the same 12-month span, the Sri Lankan rupee lost over 10 per cent and the Indonesian rupiah fell roughly 9 per cent, whereas the Malaysian ringgit and Chinese yuan both appreciated by around 4 per cent.
A stronger taka lowers the cost of essential import bills—including fuel, industrial raw materials, and staple commodities—while easing local-currency debt servicing for foreign loans. Whether this performance reflects a temporary consolidation or a permanent turnaround will depend on future export receipts, remittance durability, and international commodity market developments.