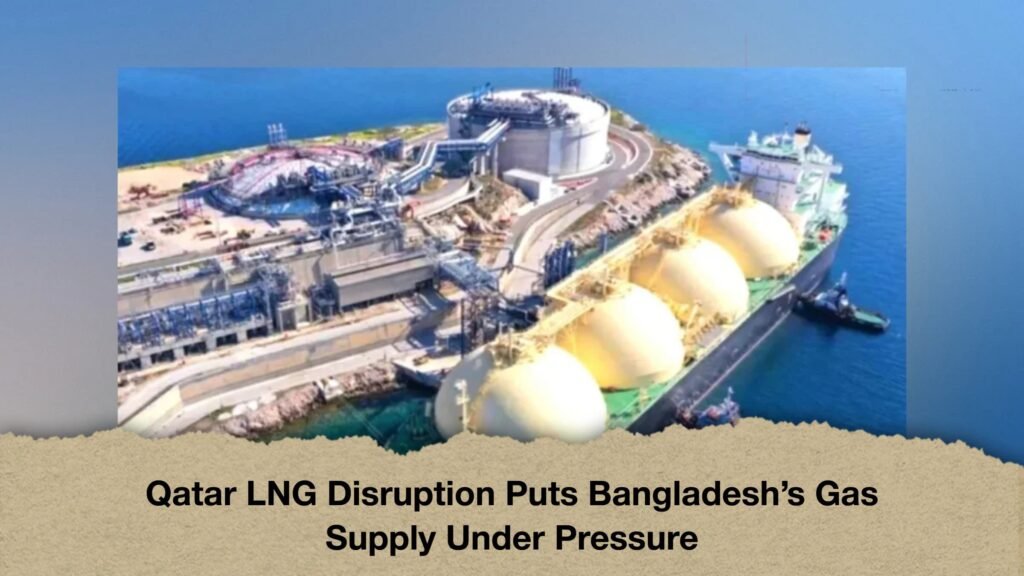
Bangladesh is facing renewed uncertainty over its energy supply after Qatar extended a force majeure period affecting LNG deliveries to Bangladesh, Pakistan and several other Asian buyers until November. The development comes as the country is already struggling with a substantial gap between gas demand and available supply.
The consequences could extend well beyond power plants and industrial facilities. Households are also exposed. When pressure in the pipeline network falls, many consumers turn to liquefied petroleum gas (LPG) cylinders for cooking. But LPG users are now facing another problem, with reports of cylinders being sold for several hundred taka above the government-set price in some areas.
Bangladesh is therefore dealing with three interconnected pressures: uncertainty over imported LNG, declining domestic gas production and higher retail costs for an alternative household fuel.
Why Qatar’s LNG supply has become uncertain
QatarEnergy announced on 28 September that force majeure affecting LNG deliveries to Bangladesh, Pakistan and several Asian buyers had been extended until November because of the situation surrounding the Strait of Hormuz.
For Italian energy company Edison, the suspension has been extended until early December.
The decision does not mean that Qatar has singled out Bangladesh or completely stopped exporting LNG. The disruption is linked to the wider conflict in the Middle East and security concerns surrounding the Strait of Hormuz, one of the world’s most important energy shipping routes.
Some LNG cargoes continued to pass through the strait in September. The concern, therefore, is not that Qatari gas has disappeared altogether, but that the reliability and timing of future deliveries have become less certain.
That matters greatly to Bangladesh because imported LNG has become a significant part of the country’s overall gas supply.
Bangladesh already has a sizeable gas deficit
Bangladesh’s daily gas demand is around 3.8 billion cubic feet (bcf), while recent supply has been approximately 2.6 to 2.7 bcf a day. This leaves a daily shortfall of roughly 1.1 to 1.2 bcf.
Domestic gas production contributes around 1.6 bcf, while LNG supplies about 1 bcf to the system.
The underlying problem is not new. Production from older gas fields has been declining, while efforts to explore new reserves and develop additional wells have not yet been sufficient to close the gap.
As domestic production falls short, Bangladesh has become increasingly reliant on imported LNG. That reliance, however, comes with financial and logistical risks. LNG has to be purchased with foreign currency, secured in a competitive international market and transported by sea before it can enter the national gas network.
The risks become greater when geopolitical tensions threaten major shipping routes.
Maheshkhali remains a critical link
Imported LNG enters Bangladesh’s national gas network primarily through two floating storage and regasification units, or FSRUs, at Maheshkhali.
These facilities are not conventional gas storage depots. LNG arrives by ship in liquid form and is then converted back into gas through regasification before being supplied to the national grid.
This makes the Maheshkhali terminals a crucial part of Bangladesh’s energy infrastructure. A disruption at one of the facilities can reduce the amount of imported gas available to the national network.
In July, gas supplies fell following an accident involving one FSRU. Supply subsequently increased after repairs. Bad weather also disrupted LNG-related operations in September.
The incidents demonstrate how several different factors can affect Bangladesh’s gas supply. A technical problem at a terminal, severe weather or instability along a major international shipping route can each create pressure on an already constrained system.
Gas shortages are increasing pressure on LPG
The effects are increasingly being felt by households. When pipeline gas pressure drops, consumers often switch to LPG cylinders for cooking, increasing demand for the alternative fuel.
In September, the government-set price for a 12-kilogram LPG cylinder was Tk 1,585. Yet reports from Dhaka and other areas suggested that cylinders were being sold for Tk 2,000 or more.
In some locations, consumers reportedly faced prices Tk 500 to Tk 600 above the official rate.
Government authorities and LPG importers, however, have said that the country does not face an overall shortage of LPG. According to their position, the problem is primarily related to reduced availability at the retail level and allegations of sales above the officially determined price.
District administrations have been instructed to investigate the matter and monitor the market. This indicates that the LPG problem involves not only international supply conditions but also the domestic distribution chain.
Alternative LNG sources may offer temporary relief
If Qatari deliveries remain uncertain, Bangladesh may need to increase purchases from alternative suppliers, including Oman and the United States, while also turning to the spot market for additional cargoes.
Such purchases could help cover an immediate shortfall, but they may come at a higher cost. LNG prices are influenced by global demand and supply conditions, meaning a rise in international prices would increase Bangladesh’s import expenditure.
Seasonal demand could add another complication. During the winter months, competition for LNG cargoes can intensify between major markets in Europe and Asia. That could make securing additional supplies more expensive and difficult.
For Bangladesh, therefore, increasing imports may provide short-term protection but cannot by itself resolve the structural weaknesses in the gas sector.
Domestic exploration remains crucial
A more durable response requires Bangladesh to strengthen its domestic gas supply. Production from mature fields is declining, making exploration for new reserves increasingly important.
Faster exploration onshore and offshore, the development of new wells and efforts to bring viable reserves into production could help reduce pressure on LNG imports.
At the same time, reducing excessive dependence on gas for electricity generation and industrial activity would make the energy system more resilient. Diversifying the fuel mix would help limit the impact of disruptions affecting a particular source or supply route.
The issue ultimately extends far beyond the availability of gas for cooking.
A delayed LNG cargo can place additional pressure on gas-fired power plants. Lower gas availability can disrupt industrial production and raise operating costs. Those higher costs can eventually feed through to the prices paid by consumers.
For households, the impact can be immediate. If pipeline gas becomes unreliable and LPG prices rise above the official rate, families face higher cooking costs.
The uncertainty surrounding Qatar’s LNG deliveries has therefore exposed a wider challenge for Bangladesh’s energy security. In the short term, the country needs to secure alternative supplies and ensure effective distribution. Over the longer term, it needs to strengthen domestic exploration, improve supply infrastructure and reduce excessive dependence on imported fuel.
The central question is whether Bangladesh is sufficiently prepared to withstand a disruption in LNG shipments without allowing pressure to spread from the gas grid to power generation, industry and household kitchens.